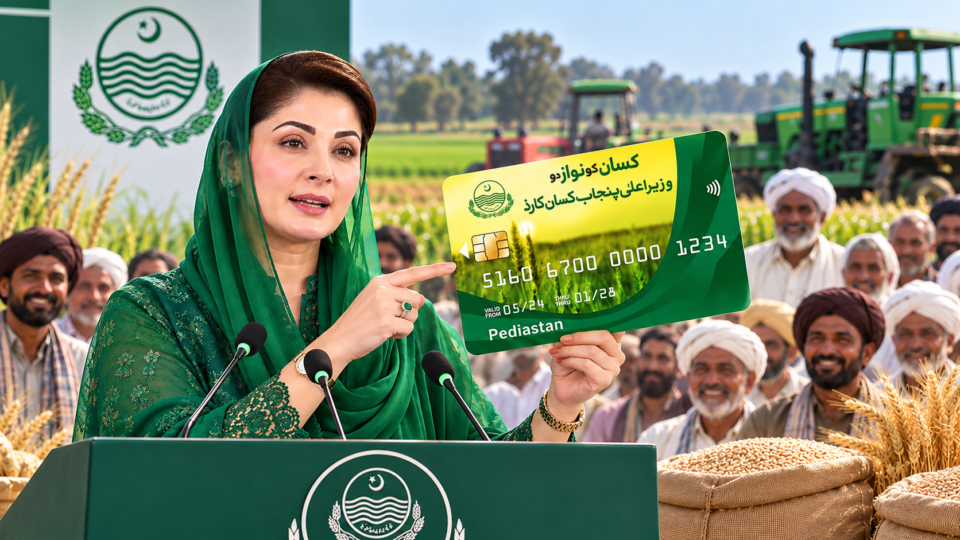
The Punjab government has announced the establishment of the province’s first Apna Kisan Bank, introducing a new initiative aimed at improving farmers’ access to affordable agricultural financing. Chief Minister Maryam Nawaz Sharif announced the measure on October 28, 2026, alongside a wider package of support for small, medium and large-scale farmers. The plan includes interest-free loans, increased financing through the Kisan Card, support for wheat cultivation, agricultural machinery subsidies and measures to improve irrigation and crop production.
Under the announced financing arrangement, farmers will be eligible for loans of up to Rs10 million without markup. Higher financing tiers have also been announced, with loans of up to Rs30 million carrying a reported 2 per cent interest rate and loans of up to Rs50 million carrying a 5 per cent rate. The initiative is intended to reduce the financial pressure on farmers who need money to purchase seeds, fertilisers, pesticides, machinery and other essential agricultural inputs.
The announcement comes as agricultural producers continue to face challenges related to production costs, access to credit, water availability, machinery expenses and unpredictable market conditions. For many farmers, securing financing at the right time can determine whether they can prepare their land, purchase quality inputs and complete planting activities within the appropriate season. The proposed bank could provide an additional channel for agricultural finance, although its operating procedures, application process and detailed eligibility requirements have not yet been fully explained publicly.
What Is Apna Kisan Bank?
Apna Kisan Bank is a proposed agricultural financing initiative announced by the Punjab government to improve access to credit for the farming community. Its central objective is to make agricultural financing more accessible and affordable, particularly for farmers who face difficulties obtaining loans through conventional banking channels.
Agriculture requires investment throughout the farming cycle. Farmers need money to prepare land, purchase seeds and fertilisers, hire machinery, arrange irrigation, pay labour costs and transport their produce to markets. These expenses often arise before farmers receive any income from the crops they grow.
When financing is expensive or unavailable, farmers may delay important activities, purchase fewer inputs than required or rely on informal borrowing arrangements. These choices can increase production risks and make it harder to earn a reasonable return from farming.
The proposed Apna Kisan Bank is intended to address part of this challenge by offering agricultural loans on announced concessional terms. By reducing or lowering the cost of borrowing, the government aims to help farmers manage production expenses and invest in their agricultural operations.
However, the announcement should be distinguished from the bank’s full operational launch. Detailed information about its legal structure, management, participating financial institutions, application channels, repayment arrangements and rollout timetable was not fully available at the time of the announcement.
Interest-Free Loans of Up to Rs10 Million
One of the main elements of the new initiative is the announcement of zero-markup financing of up to Rs10 million. This means eligible borrowers would not pay markup on loans within the specified financing tier, subject to the final programme terms.
The announced financing structure includes the following reported limits:
| Loan amount | Announced financing terms |
|---|---|
| Up to Rs10 million | Zero markup |
| Up to Rs30 million | 2 per cent interest rate |
| Up to Rs50 million | 5 per cent interest rate |
These figures reflect the financing tiers reported at the time of the announcement. The final terms, including whether rates are annual, how loan limits will be applied and which applicants qualify for each tier, should be confirmed through the official programme rules once published.
The interest-free facility could help eligible farmers reduce borrowing costs and retain more of their income for agricultural investment. Farmers may be able to use approved financing for essential inputs and other eligible farming expenses, depending on the programme’s eventual conditions.
For small farmers, the timing of financing can be particularly important. Agricultural inputs are often required before sowing, while income may not arrive until months later. Access to affordable credit can help bridge this gap and reduce the need to sell crops prematurely to meet immediate expenses.
For larger farming operations, access to financing may support investment in equipment, irrigation systems and other productive assets. Nevertheless, the amount available to an individual farmer will depend on the final eligibility criteria, assessment procedures and available funding.
Kisan Card Financing Limit Increased to Rs33,500 Per Acre
Alongside the Apna Kisan Bank announcement, the Punjab government has increased the financing limit available through the Kisan Card by Rs3,500 per acre.
The reported change raises the per-acre limit from Rs30,000 to Rs33,500. The additional financing is intended to help farmers manage rising agricultural input costs, particularly expenditure on fertilisers and other items needed for crop production.
The government expects the expanded facility to benefit approximately one million farmers and cover around five million acres. The associated programme has been reported at an estimated Rs17 billion.
The Kisan Card provides eligible farmers with a way to access financing for approved agricultural inputs, including seeds, fertilisers and pesticides. A higher limit can give participating farmers additional flexibility when purchasing the supplies required for cultivation.
For example, a farmer cultivating several acres may need to purchase different types of fertiliser, arrange land preparation and pay for other inputs within a short period. An increase in the financing limit could help cover some of these expenses without requiring the farmer to arrange the full amount from personal savings.
The Kisan Card and Apna Kisan Bank are related parts of the wider agricultural support effort, but they should not automatically be treated as the same programme. The Kisan Card has its own eligibility and financing arrangements, while the proposed bank’s complete operational structure and relationship with existing facilities remain subject to further clarification.
Why Direct Financial Support Matters for Farmers
Farmers face a distinctive financial challenge because much of their expenditure occurs before they earn revenue from their crops. Land preparation, seed purchases, fertiliser application, irrigation and labour must often be paid for weeks or months before harvesting.
A shortage of working capital can affect decisions at every stage of cultivation. Farmers may reduce the quantity of fertiliser they apply, delay sowing, use lower-quality seeds or postpone necessary machinery work. These decisions can affect yields, crop quality and the income available at harvest.
Affordable agricultural financing can help farmers plan these expenses more effectively. Instead of relying entirely on savings or expensive borrowing, eligible producers may be able to access credit under more manageable terms.
Direct financial support can also improve farmers’ ability to respond to unexpected expenses. Weather damage, pest attacks, changing input prices and irrigation problems can create additional costs during the growing season. Access to suitable financing may provide some flexibility when these difficulties arise.
However, credit alone cannot solve every agricultural challenge. Farmers also need reliable access to water, quality inputs, agricultural advice, storage facilities and markets where they can sell produce at reasonable prices. The long-term impact of Apna Kisan Bank will therefore depend on how effectively it complements other agricultural services.
Wheat Support Price Set at Rs4,500 Per 40 Kilograms
The announcement also included a commitment to implement a wheat support price of Rs4,500 per 40 kilograms, equivalent to one maund. The measure is intended to provide a stated price benchmark for wheat producers and support the wider effort to improve agricultural returns.
Wheat is one of Pakistan’s most important staple crops and plays a major role in the country’s food supply. Farmers must manage expenditure on seeds, fertilisers, irrigation, land preparation, harvesting and transportation before receiving income from their crop.
A support price can influence farmers’ expectations when deciding how much wheat to cultivate and how to plan their production costs. However, the actual benefit depends on how the announced price is implemented, the procurement arrangements and the availability of buyers.
The government has also indicated that a wheat procurement plan and an online portal for digital processing will be introduced. Such arrangements could help organise the procurement process, but their precise procedures and implementation dates require official confirmation.
For farmers, clear procurement rules and timely payments are important. Even when a support price is announced, producers need to know where their wheat can be sold, what quality standards apply and how payments will be processed.
The proposed bank and the wheat support measures address different parts of the farming cycle. Affordable credit can help with production expenses, while a functioning procurement arrangement can influence the income farmers receive after harvesting.
Agricultural Machinery and Tractor Subsidies
The Punjab government has also highlighted its investment in agricultural mechanisation. Mechanisation can help farmers complete fieldwork more quickly, reduce dependence on manual labour and improve the efficiency of planting and harvesting.
According to the announced figures, approximately 25,000 tractors have already been provided to farmers through subsidised schemes. The government has also referred to a plan to offer 50,000 tractors under the Green Tractor Scheme.
In addition, Rs70 billion has been allocated to high-tech agricultural mechanisation. The wider effort includes support for machinery and equipment designed to improve productivity, reduce crop losses and make farming operations more efficient.
Access to tractors and specialised equipment can be particularly important during time-sensitive agricultural activities. Delays in preparing land or harvesting crops may lead to additional costs and, in some circumstances, reduced yields or quality.
However, purchasing machinery can be beyond the financial reach of many small farmers. Subsidies can reduce the initial cost, while equipment-rental and machinery-financing programmes can provide alternative ways to access modern technology.
The government has also discussed expanding access to high-efficiency equipment, including machinery that can help manage crop residues. Such equipment may support more efficient field operations while reducing reliance on practices that contribute to air pollution.
For the Apna Kisan Bank initiative, a key question will be whether its financing arrangements eventually support eligible investments in machinery and other productive assets. The final rules will determine which uses of funds are permitted.
Supporting Small Farmers and Improving Access to Credit
Small farmers often operate with limited financial reserves and may have fewer options when seeking credit. Their income depends on seasonal harvests, while expenses arise throughout the year.
A financing initiative designed around agricultural needs could help eligible farmers obtain funds at more suitable times. The benefit would depend on whether the application process is accessible, the eligibility requirements are reasonable and repayments are aligned with farming income.
The Punjab government has stated that more than one million small farmers are already benefiting from the Kisan Card. The programme is intended to improve access to approved agricultural inputs and reduce the need for farmers to depend on intermediaries for financing.
Officials have also indicated that steps are being considered to include tenant farmers and people cultivating land on lease in the Kisan Card programme. This issue matters because agricultural production is not limited to landowners. Many people cultivate land under rental or tenancy arrangements and may face difficulties proving eligibility under schemes designed around land ownership.
The final rules for Apna Kisan Bank will need to clarify how tenant farmers, leaseholders, small landowners and larger agricultural producers will be assessed. Clear requirements can help applicants understand what documents they need and whether they qualify for support.
Transparent selection procedures and accessible complaint mechanisms would also be important for ensuring that eligible farmers can use the programme fairly.
Improving Irrigation and Preventing Water Theft
Financial assistance is only one part of agricultural development. Reliable irrigation is also essential for maintaining crop production, particularly in areas where rainfall is insufficient or irregular.
The Punjab government has announced continued action against water theft, with the stated objective of ensuring that irrigation supplies reach farmers throughout canal systems, including those located at the tail end of watercourses.
Farmers who receive insufficient water may face reduced yields even when they have purchased seeds and fertilisers on time. Unequal distribution can also create disputes between farmers and increase the difficulty of planning crop schedules.
The government has also highlighted canal desilting and the lining of watercourses as measures intended to improve water delivery and reduce wastage. Better-maintained irrigation infrastructure can help water move more efficiently through agricultural areas.
In addition, the administration has discussed expanding high-efficiency irrigation systems and developing water resources in the Potohar region. The reported initiatives include 400 mini dams completed in the region, with plans to increase the total to 1,000.
The benefits of these measures will depend on maintenance, water availability, local requirements and how effectively the infrastructure is managed. Farmers also need practical guidance on efficient irrigation methods and the crops best suited to their conditions.
Affordable financing may help some farmers invest in water-saving equipment, but any such use under Apna Kisan Bank would depend on the final lending rules.
Soil Testing and Agricultural Advisory Services
The provincial government has also announced mobile laboratories for soil-fertility and water testing. These facilities are intended to help farmers understand the condition of their land and irrigation water so that they can make better-informed production decisions.
Soil testing can provide information about nutrient levels and other characteristics that influence crop growth. Using this information, farmers can make more targeted decisions about fertiliser application rather than relying entirely on general recommendations.
Appropriate fertiliser use can help reduce unnecessary expenditure and improve nutrient management. Testing irrigation water can also help identify issues that may affect soil health or crop development.
Mobile laboratories may be particularly useful for farmers who live far from specialised agricultural facilities. Their practical value will depend on how often services are available, the speed of test results and whether farmers receive understandable advice about the findings.
The government has also reported deploying agriculture interns to support farmers in the field. Such advisory services can complement financial programmes by helping farmers decide how to use inputs efficiently.
Together, access to credit, soil testing, agricultural guidance and reliable irrigation can address several different barriers to productivity. Their combined effectiveness will depend on coordination between the relevant departments and the needs of individual farming communities.
Promoting Olive Cultivation and Agricultural Diversification
Another part of the Punjab government’s agricultural package focuses on promoting olive cultivation through a special support package and subsidies.
Agricultural diversification can provide farmers with alternatives to relying entirely on traditional seasonal crops. Depending on local conditions, suitable olive varieties and effective farm management, olive production may create opportunities for additional income and value-added products.
The government has also highlighted the potential for developing facilities for olive-oil extraction. Processing facilities can help agricultural producers move beyond selling raw produce and participate in higher-value parts of the supply chain.
However, olive cultivation requires appropriate growing conditions, investment and time before trees produce commercially useful yields. Farmers need reliable information about suitable land, irrigation requirements, planting material, maintenance and potential markets before making long-term decisions.
Any financing support for olive cultivation would need to account for the time between initial investment and commercial production. The final terms of Apna Kisan Bank will determine whether such long-term agricultural investments qualify for loans.
Diversification can contribute to rural economic development, but the results will depend on practical implementation, market demand and the ability of farmers to manage production and processing costs.
Agricultural Processing Parks and Better Market Access
The government has also announced plans for agro-processing parks in Sargodha, Bhakkar, Khanewal and Okara. The proposed facilities are intended to support grading, processing and storage of agricultural produce, including mangoes, kinnow, oranges, potatoes and other crops.
Post-harvest losses can reduce farmers’ earnings when produce spoils, is damaged during transport or cannot be sold quickly enough. Storage and processing facilities can provide more options for handling crops and potentially extend the period in which produce can be marketed.
Grading and packaging can also help producers meet the requirements of different buyers. Processing may create opportunities to supply products with greater value than unprocessed produce, although success depends on market demand, operating costs and quality standards.
For farmers, improved market access is important because higher production does not always translate into higher income. Prices can fall when many producers harvest the same crop at the same time, while inadequate storage can force farmers to sell quickly.
The proposed Apna Kisan Bank could potentially complement these developments by improving access to working capital, but its final lending rules will determine whether financing is available for storage, processing or related business investments.
A coordinated approach involving finance, infrastructure, market information and agricultural advice would be necessary to improve the overall position of farmers.
Livestock Development and Rural Employment
The announced package also includes measures related to livestock farming. The government has reported that approximately 400,000 animals were fattened during the previous year and has set a target of preparing another 600,000 animals during the current year.
Livestock contributes to rural livelihoods through meat, milk and other agricultural products. It can also provide income opportunities for households that combine animal farming with crop cultivation.
Livestock production requires spending on feed, veterinary care, housing and animal management. Farmers need access to suitable markets and reliable information about animal health, nutrition and production costs.
Support programmes can help improve livestock management, but their results depend on access to veterinary services, quality feed, effective disease prevention and market opportunities.
If the Apna Kisan Bank eventually supports eligible livestock-related activities, clear financing rules would help applicants understand which expenses and investments qualify. Until those rules are published, farmers should not assume that every livestock expense will automatically be covered.
Environmental Measures and Crop Residue Management
The Punjab government has also urged farmers not to burn crop residues, linking the request to efforts to reduce smog and improve air quality.
Burning leftover plant material after harvesting can contribute to air pollution, particularly when it occurs alongside emissions from transport, industry and other sources. Poor air quality can affect public health and disrupt daily life across the province.
Farmers may need practical and affordable alternatives to residue burning. Depending on the crop and local conditions, machinery can help manage residue or incorporate it into agricultural operations.
The government’s investment in high-tech mechanisation may therefore have environmental as well as productivity-related objectives. Equipment such as specialised seeders can help farmers manage residues while preparing land for the next crop, provided it is suitable for the farming system.
However, access to machinery, operating costs and local availability can influence whether farmers adopt alternative practices. Support programmes are more likely to be useful when they combine clear environmental guidance with practical equipment and affordable services.
What Farmers Need to Know Before Applying
Although the Apna Kisan Bank has been announced, farmers should wait for the formal programme instructions before making financial decisions based on its proposed facilities.
The detailed application process, eligibility requirements, required documents, participating institutions and loan-disbursement schedule were not fully specified in the available announcement. Farmers should confirm these details through official provincial channels when the programme information becomes available.
Applicants may wish to prepare basic agricultural and identity records, including valid identification, information about the land they cultivate and details of their farming activities. However, these should be treated as general preparation rather than a confirmed list of documents required by the new bank.
Farmers should also distinguish between zero-markup loans and other concessional financing tiers. A zero-markup facility may carry no markup on the eligible loan amount, while other tiers can have different interest rates and repayment conditions.
Before accepting any loan, applicants should review the repayment schedule, eligible uses of funds, late-payment conditions and any administrative charges stated in the official terms. They should also avoid relying on unofficial agents who promise guaranteed approval or request unnecessary payments.
Clear communication from the government will be important to ensure that farmers understand the scheme and can determine whether it meets their financial needs.
Potential Impact on Punjab’s Agricultural Economy
Punjab is a major centre of Pakistan’s agricultural production, and changes affecting its farming sector can have wider consequences for food supplies, rural employment and related industries.
Improved access to agricultural finance can help farmers purchase inputs, invest in equipment and plan production more effectively. If the financing reaches eligible applicants on appropriate terms, it may help reduce some of the barriers associated with seasonal cash shortages.
The wider package also addresses areas beyond lending, including irrigation, soil testing, mechanisation, livestock development, crop procurement and agricultural processing. These measures target different stages of the production cycle and could complement one another if implemented effectively.
However, announcing a programme is only the first step. Its practical impact will depend on the funds made available, the number and profile of eligible beneficiaries, the speed of disbursement, administrative transparency and the ability of farmers to repay loans under the agreed conditions.
The government will also need to communicate results clearly so that farmers can assess how the scheme is working. Useful measures could include the number of applications received, approvals issued, loans disbursed, participating districts and the distribution of financing between different types of farmers.
Such information would help establish whether the initiative is reaching the intended beneficiaries and whether its financing arrangements are meeting agricultural needs.
Conclusion
The Punjab government has announced the establishment of Apna Kisan Bank as part of a wider programme intended to provide more affordable financing and direct support to farmers. The announced measures include zero-markup loans of up to Rs10 million, additional concessional financing tiers, an increase in Kisan Card financing from Rs30,000 to Rs33,500 per acre, and a commitment to implement a wheat support price of Rs4,500 per 40 kilograms.
The wider package also covers tractor subsidies, high-tech agricultural machinery, irrigation improvements, soil and water testing, olive cultivation, livestock development and agro-processing facilities. Together, these measures address several financial and operational challenges faced by agricultural producers.
For farmers, the key question will be how the new bank operates in practice. Clear eligibility rules, accessible applications, transparent loan approvals and timely disbursement will be important in turning the announcement into usable support.
If implemented effectively, the initiative could provide another route for eligible farmers to finance agricultural activities and manage production costs. Its long-term results will depend on the final programme terms, the quality of implementation and whether the financing reaches farmers who need it most.
Join the Conversation
Share your thoughts, questions, or feedback below.